
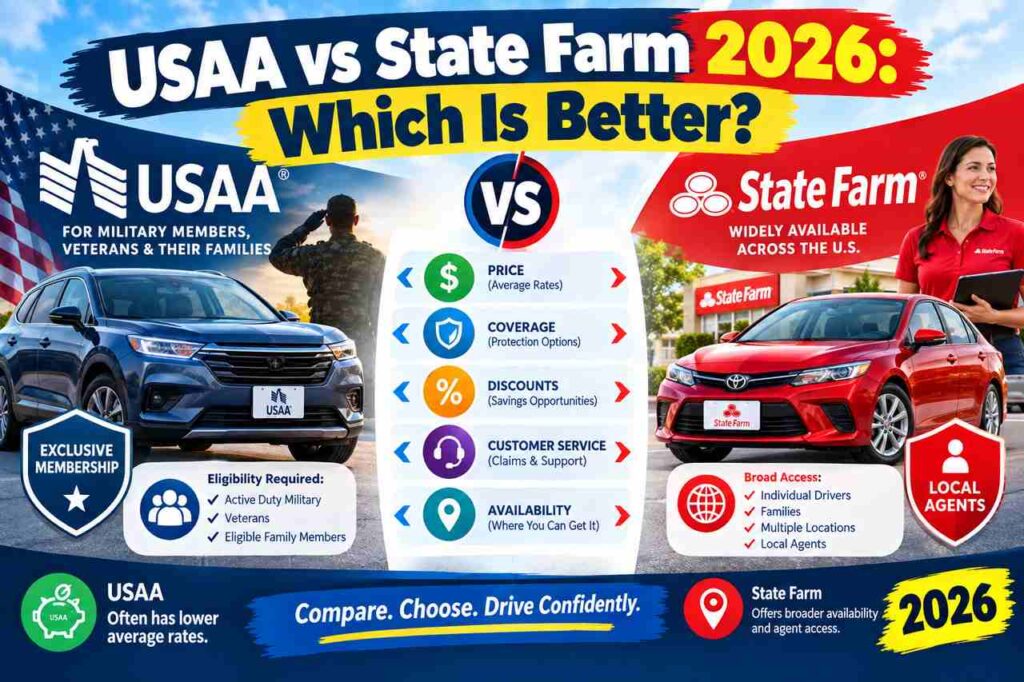
USAA vs State Farm 2026: Which Is Better?
If you’ve got any military connection, this one’s almost unfair — USAA really is that good. For everyone else, State Farm is the realistic pick. Either way, it helps to see how the two measure up.

If you’ve got any military connection, this one’s almost unfair — USAA really is that good. For everyone else, State Farm is the realistic pick. Either way, it helps to see how the two measure up.
When you’re staring down a gap in coverage — say, between jobs — short-term insurance looks like a cheap, easy fix. Sometimes it is. But it comes with real catches worth understanding before you sign anything.
A life insurance policy approved in minutes, no needle in sight — that’s normal now, not a gimmick. And for healthy people it barely costs more than the old way, which changes the whole calculation.
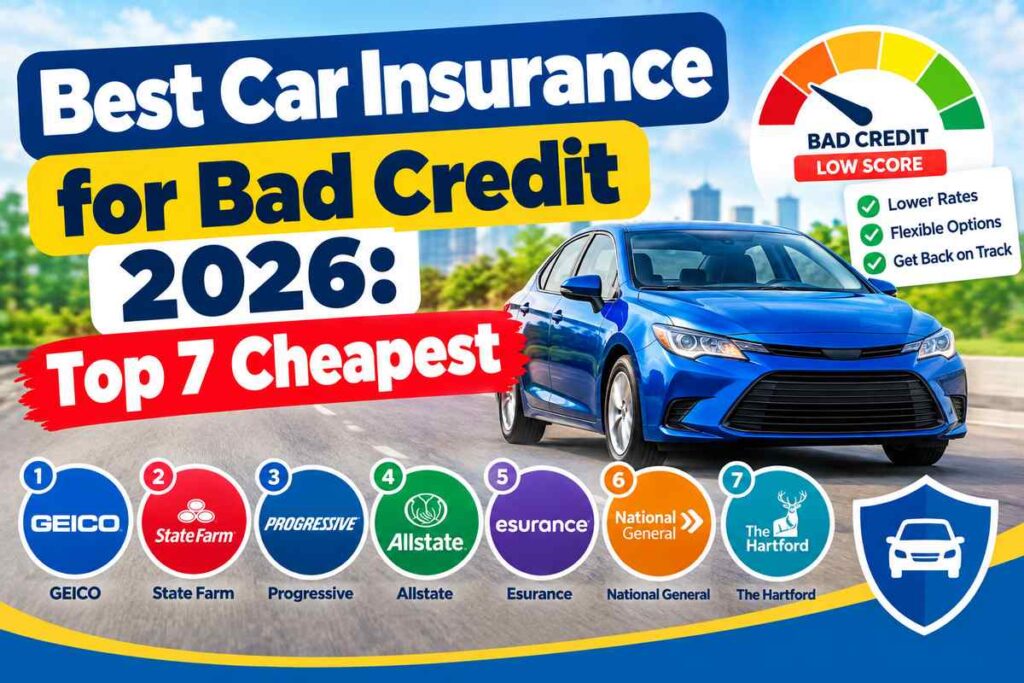
In most states, your credit score shapes your car insurance bill about as much as your driving does. Since insurers weigh it very differently, the right one can mean real savings while your score recovers.
The cheapest family plan on paper isn’t always the cheapest once you factor in the kids’ doctor and a possible CHIP spot for them. A couple of quick checks before you enrol can quietly save you hundreds.
Later in life, the right policy is usually a small one — just enough to cover a funeral, no more. The trick is knowing which companies do that cheaply, and which clauses to read twice before you sign.
Two of the biggest names, endless ads, and one honest question underneath: which is actually cheaper for you? The real answer comes down to your driving record — so let’s put them side by side.
This is the question that trips up almost everyone, usually because someone’s pushing the pricier option. Let’s clear it up calmly — what really separates the two, and which one your situation actually calls for.
Whole life might be the most oversold product in insurance, usually by someone on commission. That doesn’t make it useless — here’s a straight, no-pressure look at what it really costs and whether it’s for you.
When you work for yourself, health insurance lands entirely on your shoulders — and that’s exactly where the marketplace earns its keep. Between the subsidies and a tax deduction most freelancers forget, it costs less than the sticker price suggests.