
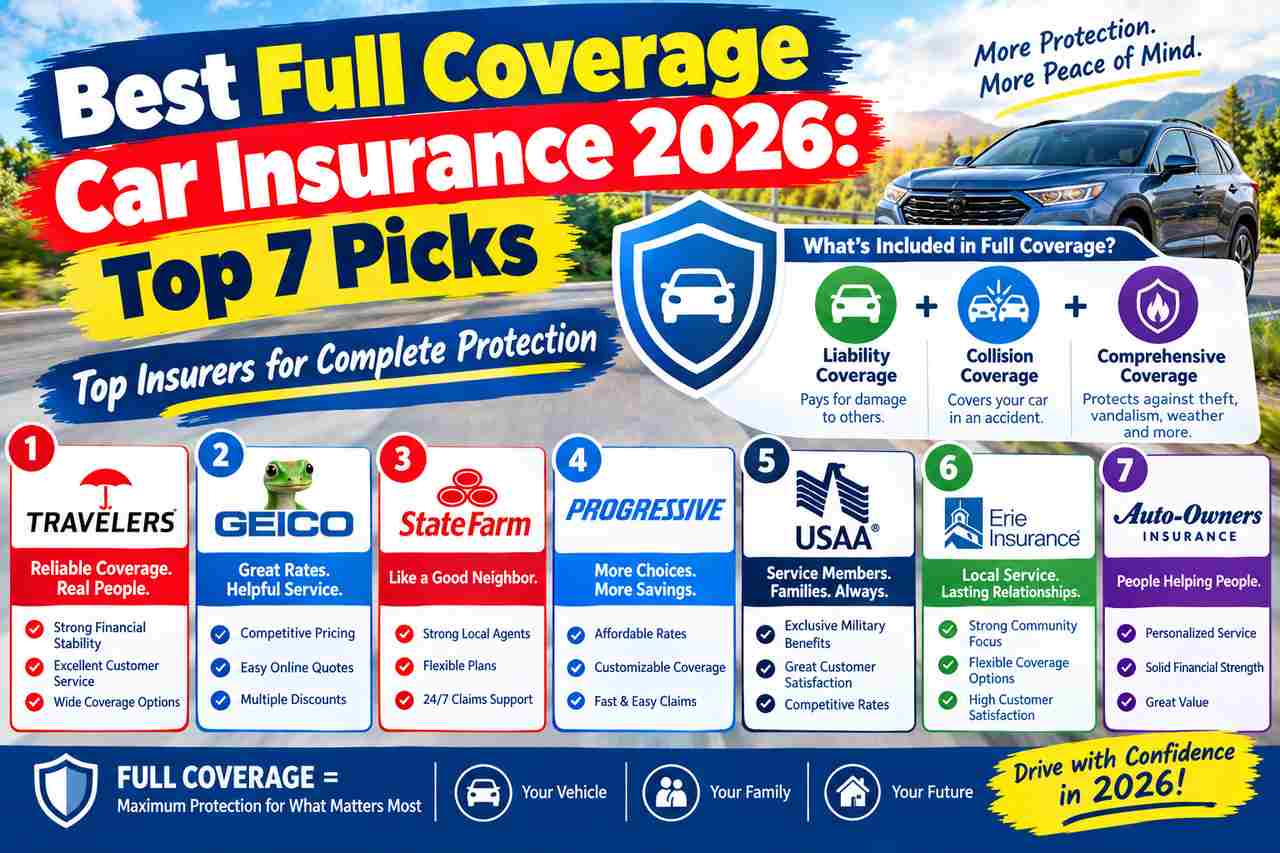
Full coverage (liability + collision + comprehensive) averages around $1,600–$2,300 a year depending on the insurer. Travelers and GEICO are usually the cheapest big names, USAA is lower if you’re military, and regional insurers like Erie can beat them where available. It’s worth it on a newer or financed car; on an old beater, it often isn’t — and knowing when to drop it is where real money hides.
Cheapest full coverage
| Company | Full coverage / yr | Note |
|---|---|---|
| Erie | ~$1,572 | 12 states + D.C. |
| USAA | ~$1,587 | Military only |
| Country Financial | ~$1,608 | 19 states |
| Travelers | ~$1,652 | Cheapest big national insurer |
| American Family | ~$1,752 | Regional, agent network |
| State Farm | ~$1,985 | Largest agent network |
| GEICO | ~$2,020 | Top app & discounts |
| Progressive | ~$2,277 | Strong for high-risk |
Sources: NerdWallet and LendingTree, 2026 averages for a clean-record driver. Varies by state, age, car and credit.
What “full coverage” actually includes
It’s not one policy — it’s three things bundled: liability (covers other people and their property when you’re at fault), collision (repairs your car after a crash), and comprehensive (theft, weather, vandalism, hitting an animal). Liability you always keep; collision and comprehensive are the parts worth questioning once your car gets old.
Is it worth it on your car?
Keep full coverage if your car is newer, financed or leased — lenders usually require it anyway. The rule of thumb for an older car: if your yearly collision + comprehensive cost is more than about 10% of the car’s value, dropping those pieces may make sense. And remember your state swings the whole bill — full coverage runs about $2,578 a year nationwide but closer to $3,900–$4,000 in Louisiana, Michigan or Florida versus ~$1,660 in Vermont.
A real example
Say you drive a 2012 sedan that’s worth about $4,000, and full coverage costs you $1,400 a year — roughly $600 of that being collision and comprehensive. If the car gets totaled, the most the insurer pays is $4,000 minus your deductible, maybe $3,500. Paying $600 a year to protect a car worth a few grand means that in five or six years you’ll have handed over more in premiums than the car is worth. That’s the moment I’d drop collision, keep solid liability, and pocket the difference.
How to pay less
Biggest levers
- Compare at least 3 insurers
- Raise your deductible to what you can cover
- Bundle home or renters with auto
- Use a telematics app if you drive safely
Don’t forget
- Drop collision/comp on an old low-value car
- Re-shop every 12 months
- Claim every discount you qualify for
- Review coverage once a car is paid off
The bottom line
Quote Travelers and GEICO (plus USAA if military, Erie if local), keep full coverage while the car is worth protecting, and raise your deductible to trim the monthly cost. On an old car, do the math and consider dropping collision. Not sure full coverage is even your cheapest path? Compare quotes in our online quotes guide.
Full coverage is something people overpay for in two opposite ways. Some keep it on a 15-year-old car that’s barely worth the deductible — if that’s you, do the math and seriously consider dropping collision. Others cut corners on a financed car and get wiped out after one bad crash.
If I were choosing, I’d keep full coverage as long as the car is genuinely worth protecting, start with Travelers or GEICO for the price, and bump my deductible up to whatever I could comfortably pay out of pocket. That single lever quietly lowers the premium every month without leaving me exposed where it counts.
FAQs
What does full coverage include?
Is full coverage worth it?
What’s the cheapest full coverage in 2026?
When should I drop collision and comprehensive?
How can I lower my full-coverage cost?
Does my state change the price much?
Sources: NerdWallet, LendingTree and Insurance.com (2026 rate data).